
Dicalcium Phosphate CAS: 7757-93-9
Dicalcium Phosphate CAS: 7757-93-9
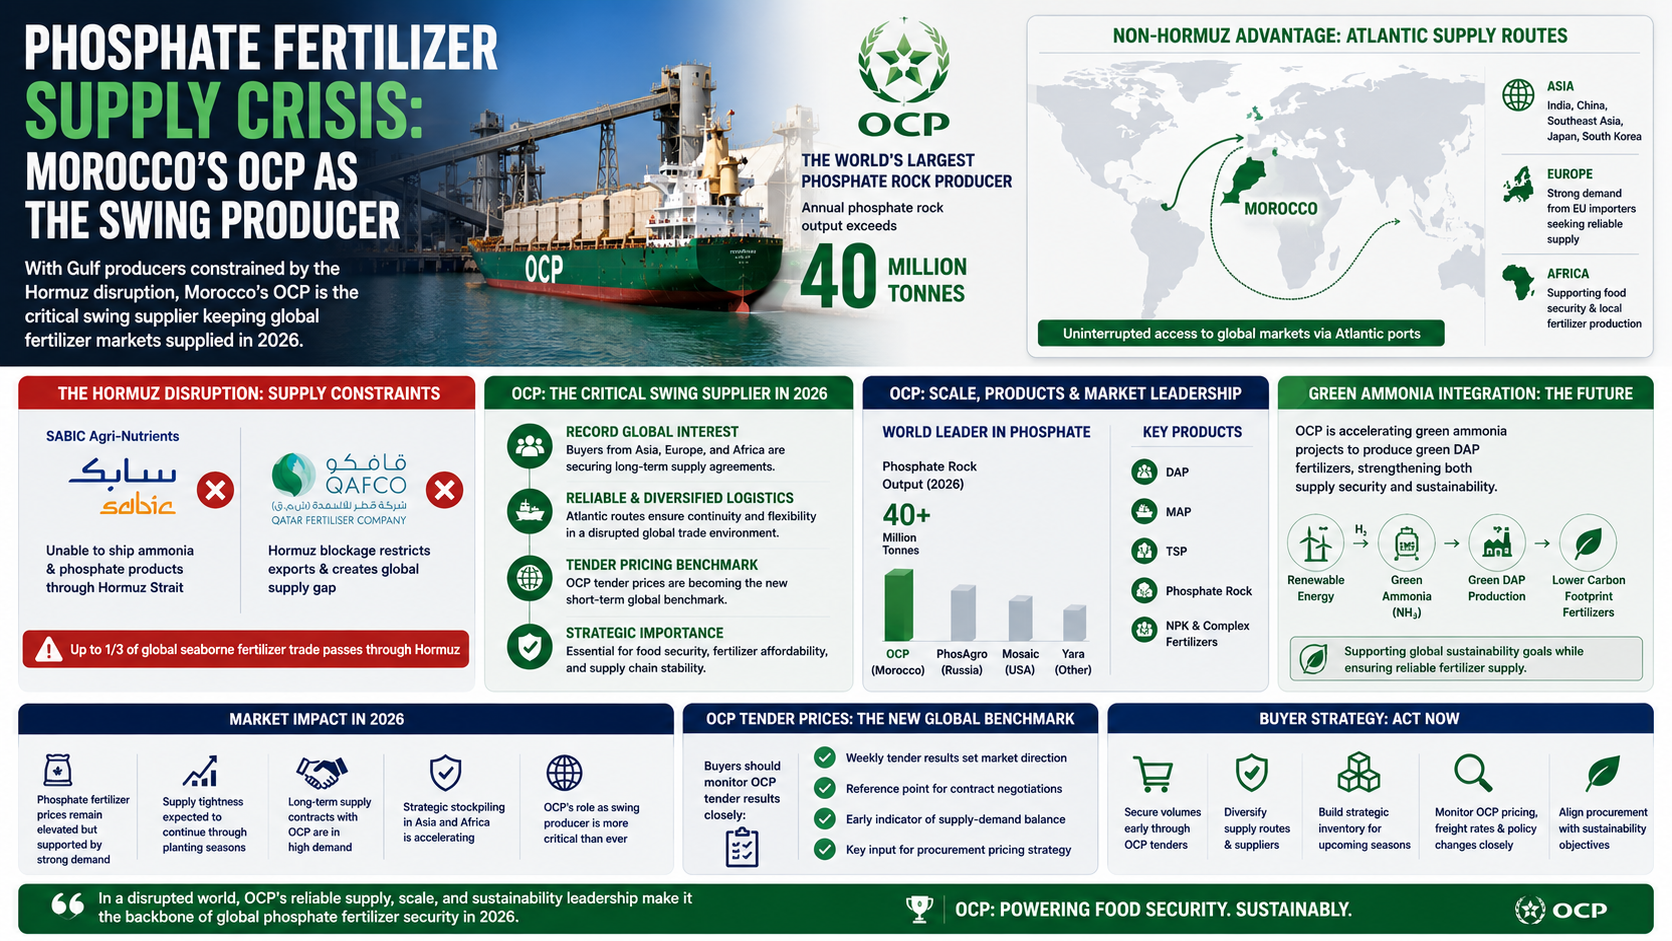
Geopolitical tensions are disrupting more than oil and gas markets. Helium and fertilizer supply chains are also under pressure, making procurement planning increasingly important for manufacturers, distributors and agricultural suppliers.
Hospital pharmacies are entering H2 2026 with improving supply conditions after months of inventory pressure. Q3 is expected to become the largest pharmaceutical chemical restocking period since before the Hormuz crisis.
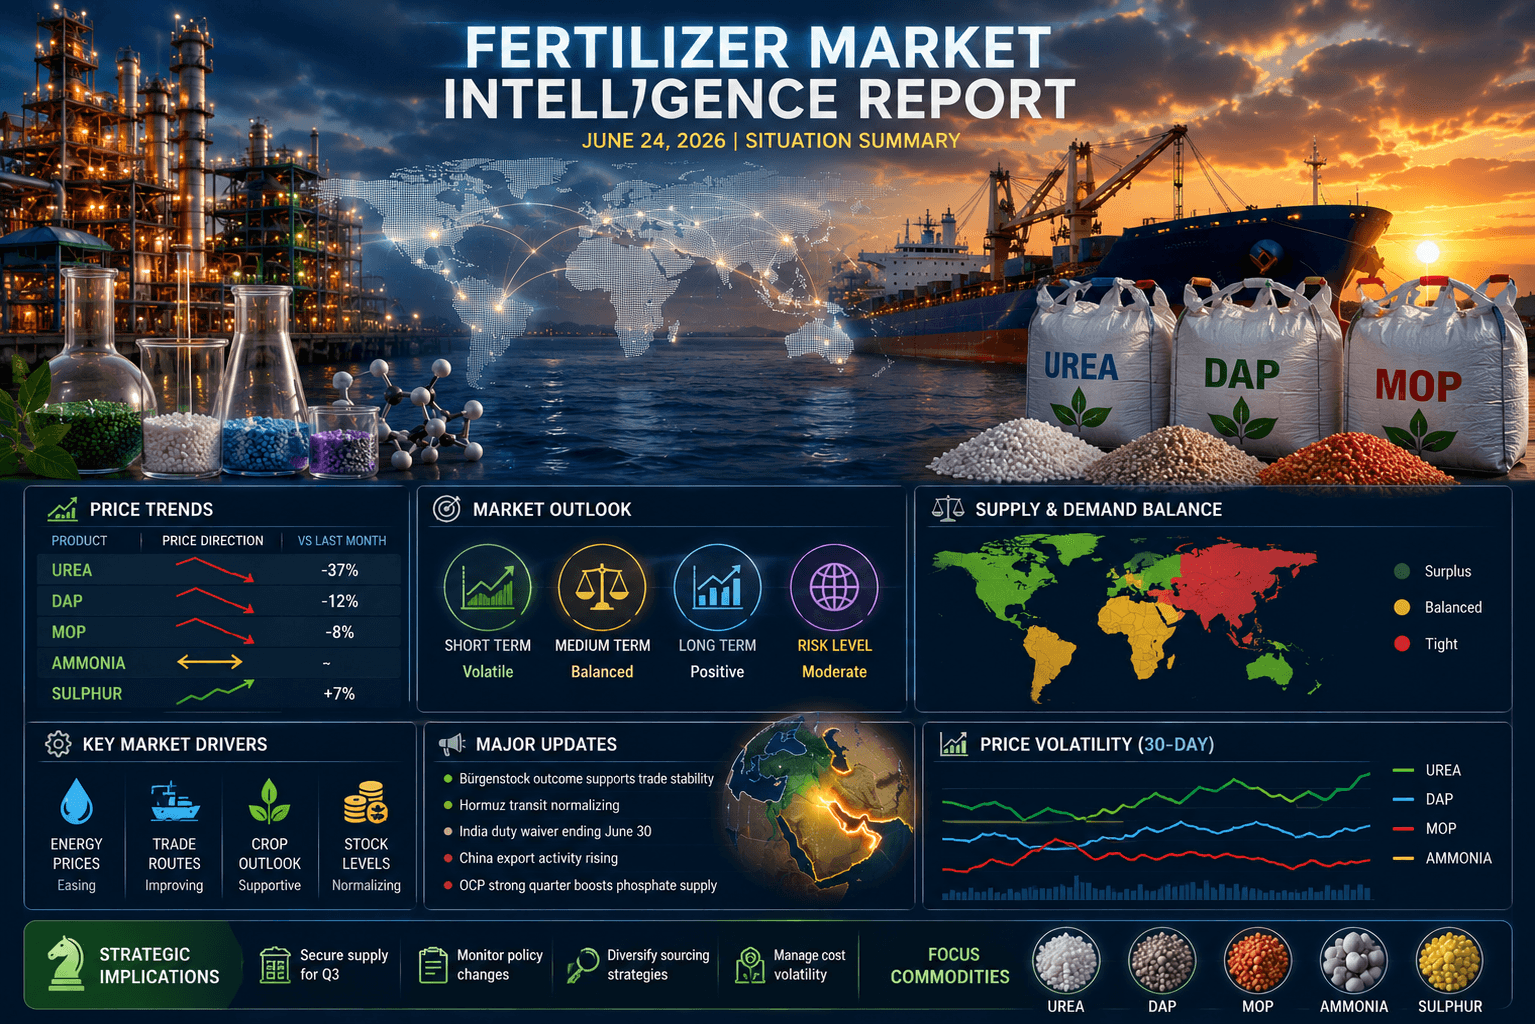
Global fertilizer markets are stabilizing after months of disruption, but June 2026 remains a critical procurement window. Urea prices are down 36%, ammonia exports may restart in July, and fertilizer buyers must navigate supply recovery, policy deadlines, and pricing uncertainty.
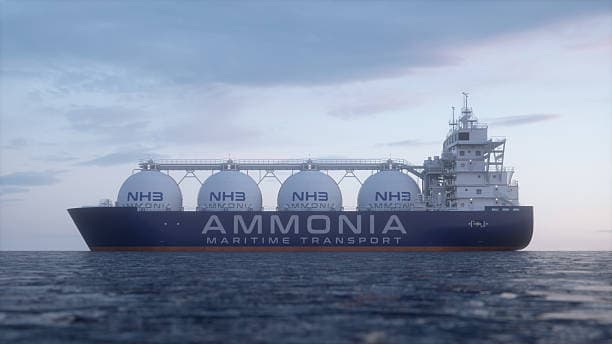
QAFCO and SABIC have restarted ammonia export operations to the Gulf, signaling a rebound in regional supply that will shape 2026 market dynamics. The move opens new sourcing options for fertilizer producers and industrial buyers, while influencing global ammonia prices and feedstock availability. Below we explore the implications for the market, pricing trends, and the broader fertilizer sector.
Urea prices in 2026 are poised for a rebound as Gulf exports climb back to 75% of pre‑war levels. This shift reshapes demand in the Southern Hemisphere, offering new buying windows for fertilizer importers. TradeAsia tracks the latest market dynamics for SABIC and QAFCO urea.
Methanol pricing outlook for Q3 2026 is entering a new phase as global buyers reassess contracts after Middle East supply concerns begin to ease. Procurement teams need to understand how energy markets, shipping routes and production recovery will influence upcoming methanol negotiations.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.