
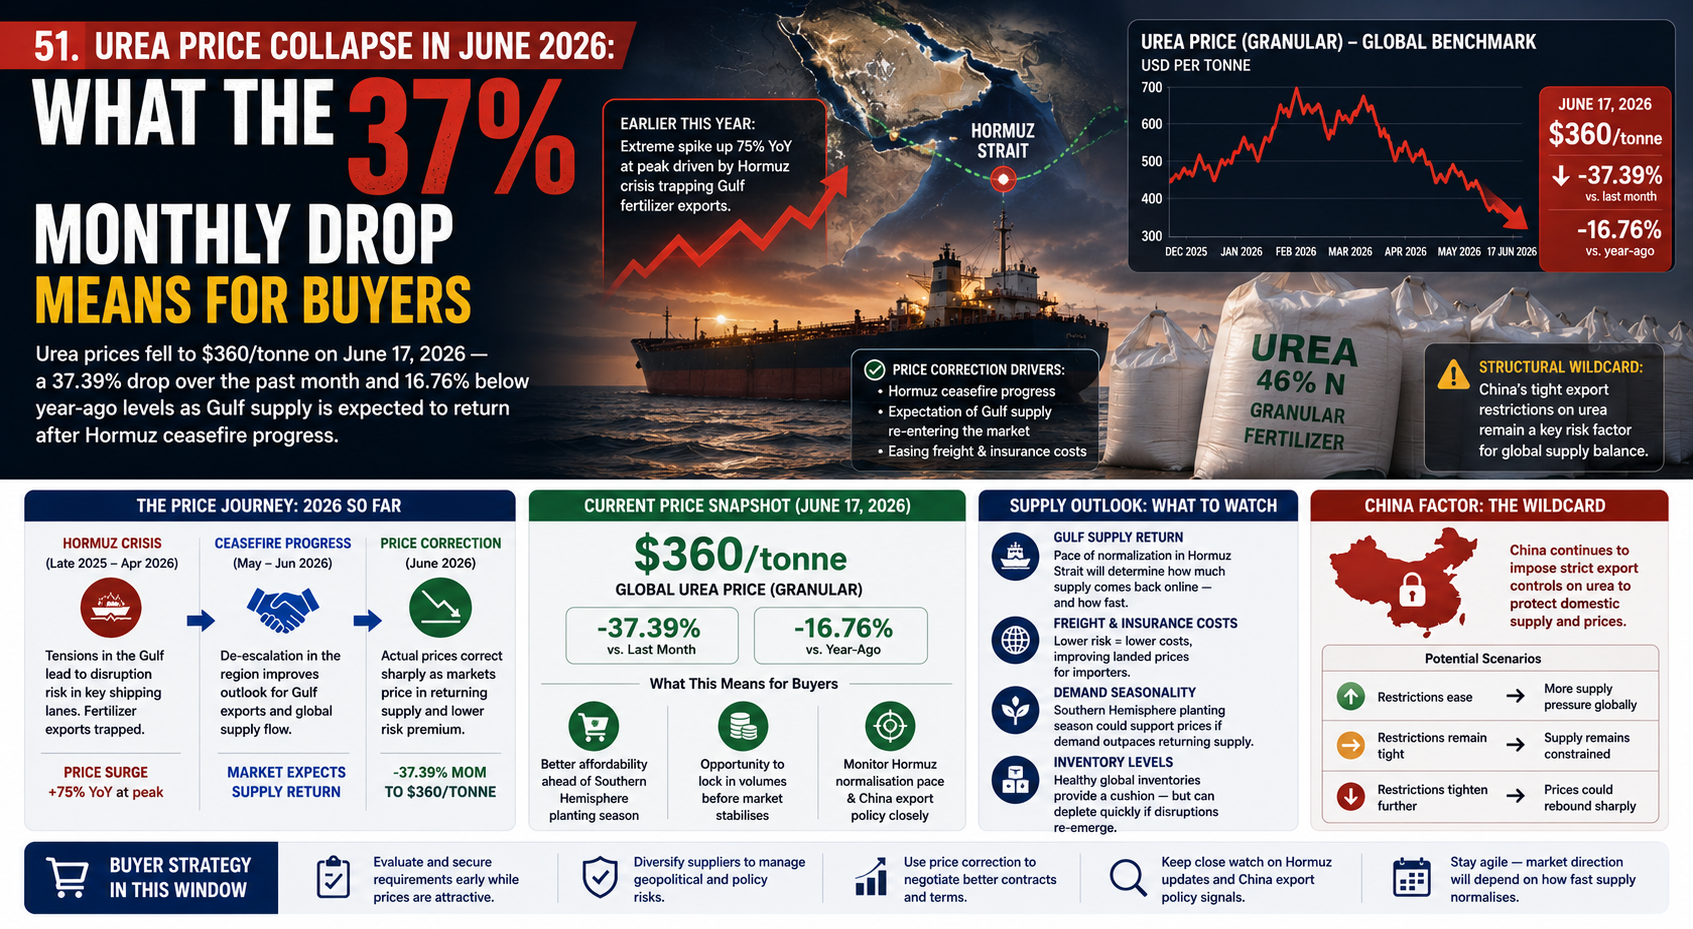
Urea (Granular) - Egypt CAS: 57-13-6
Nutrien is expected to report exceptionally strong Q2 2026 earnings as sanctions on Russian and Belarusian potash combine with Hormuz supply disruption to tighten global markets. Potash buyers should watch July guidance closely before negotiating H2 contracts.
With sports nutrition surging, maltodextrin and dextrose demand is set to rise in H2 2026. Easing freight rates unlock new procurement windows, especially in China and emerging markets. This article explores market dynamics, supply trends, and strategic sourcing tips for buyers.
Northeast Asia’s benzene market is showing early signs of recovery as cracker operations improve and Gulf supply routes reopen. This analysis explains how gradual supply restoration may affect downstream chemical buyers in Q3 2026.
As crude oil prices move below $80 per barrel, specialty chemical producers are preparing for lower feedstock costs across solvents, surfactants, coating resins, and polymer additives. However, cost pass-through in specialty chemicals typically lags by 6–10 weeks, meaning Q3 contract negotiations remain critical for buyers seeking to capture expected price declines during the second half of 2026.
Unlike many chemical markets affected by the Hormuz disruption, electronic chemicals remain constrained due to structural semiconductor demand driven by AI and advanced chip manufacturing. Buyers should not expect supply conditions to ease alongside broader chemical markets in H2 2026.
Strong exports from Belarus and Russia are helping stabilize potash markets despite ongoing fertilizer demand growth.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.