
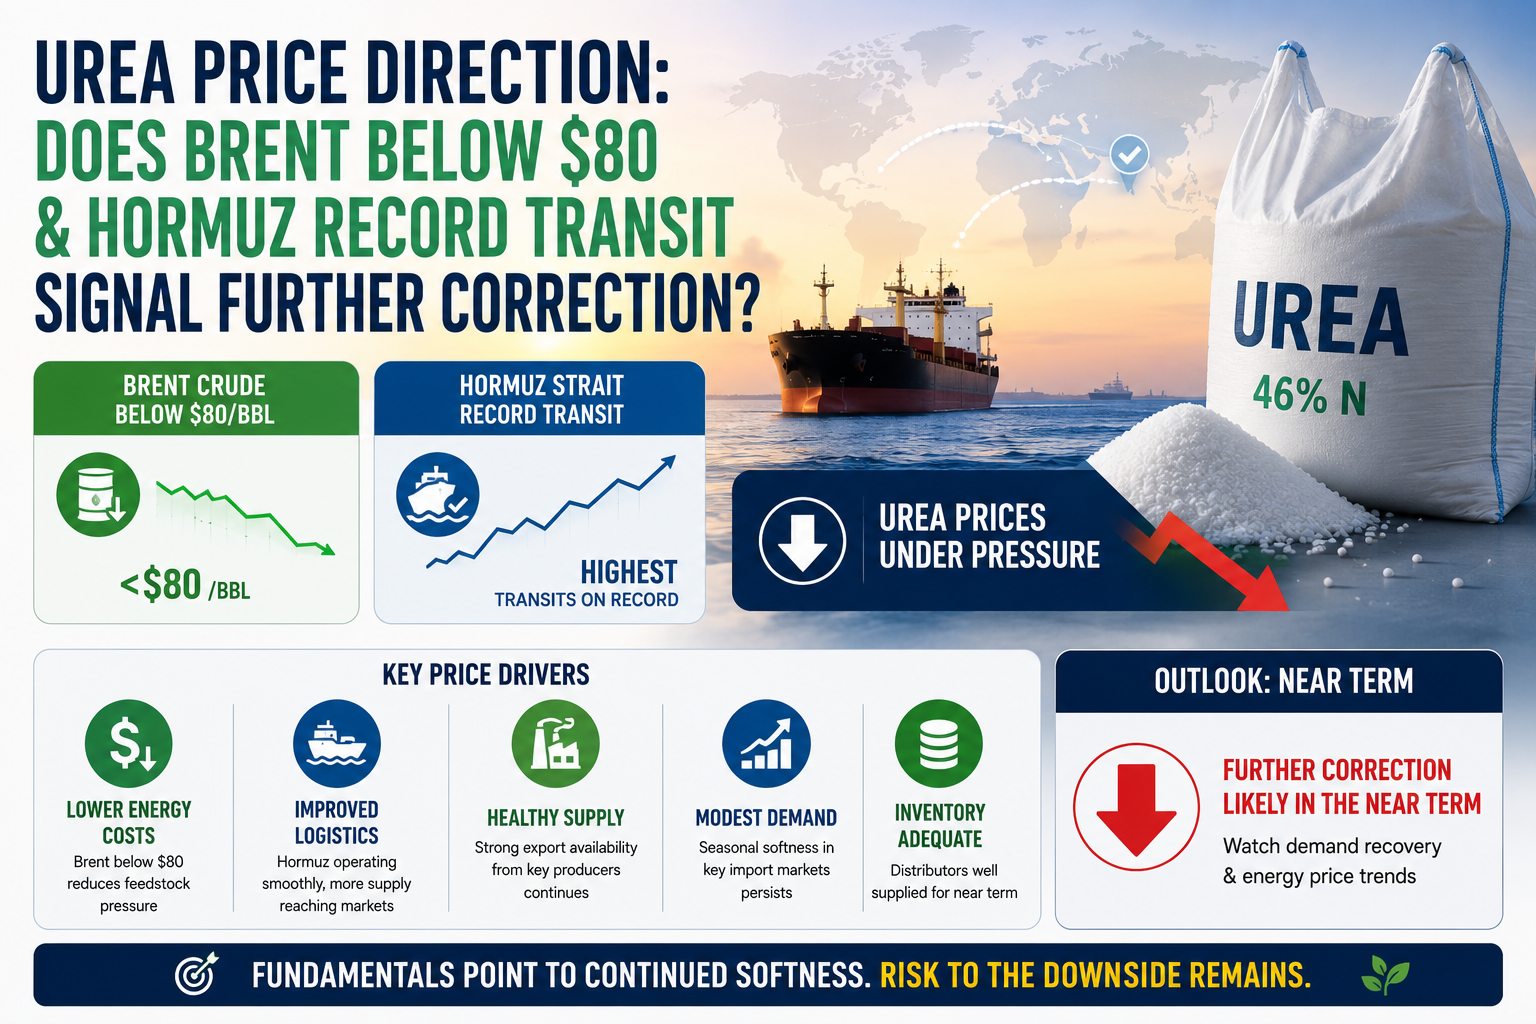
Urea (Granular) - Egypt CAS: 57-13-6
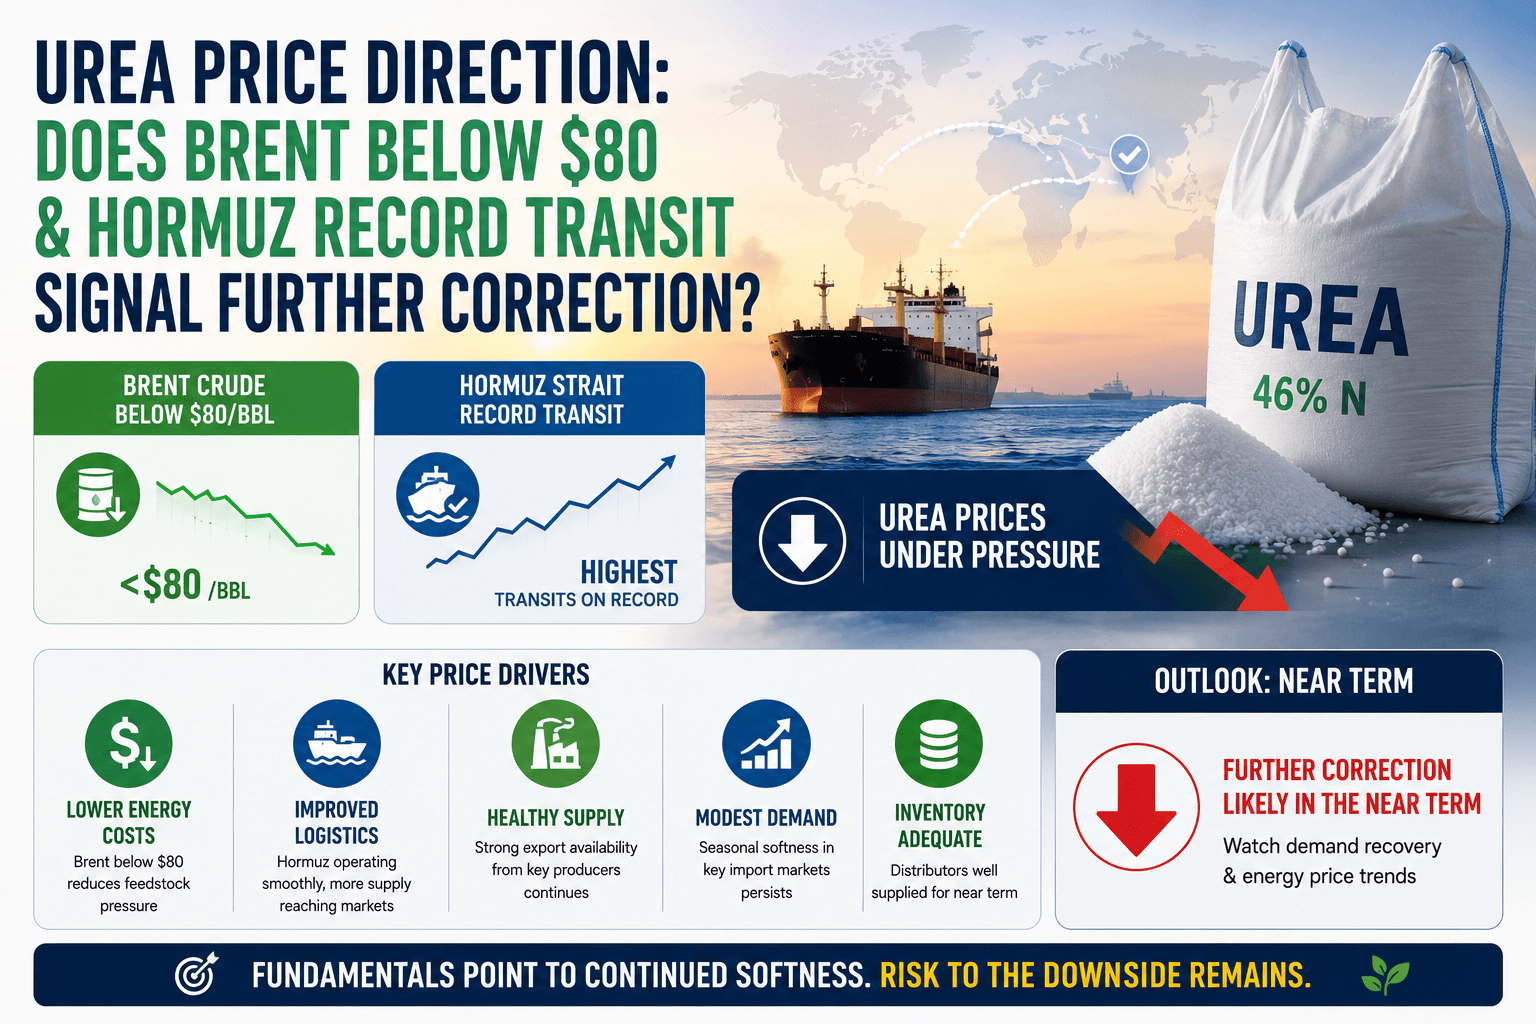
Urea (Granular) - Egypt CAS: 57-13-6
Hydrogen peroxide supply in Europe is entering a tighter phase after Solvay plant closures reduced regional production capacity. Buyers in bleaching, water treatment and industrial sectors need to evaluate alternative sourcing strategies as energy costs and supply availability shape the market.
Chinese refining and chemical producers sharply increased price quotations for aromatics and alcohols on July 1, 2026, creating fresh challenges for downstream manufacturers and procurement teams. Buyers should understand what triggered the repricing wave and how it may influence future sourcing strategies.
Caustic soda and soda ash markets closed H1 2026 with more stable conditions compared with several crisis-affected chemical segments. Buyers can use current trends as a reference point for H2 procurement planning and cost assessments.
India’s tight fertilizer market finds relief as OCP Morocco dispatches triple superphosphate (TSP) shipments, replenishing stocks and supporting crop plans. Yet, global supply constraints keep the market volatile. The article explores the impact of these cargoes and future outlook.
Falling Brent crude prices are creating the first meaningful freight cost correction opportunity since the 2026 shipping crisis began. Chemical buyers should use the July 1 bunker surcharge reset to renegotiate freight contracts and push back against outdated crisis-era shipping costs.
The June 2026 fertilizer intelligence report covers the volatile first half, examines Gulf supply recovery, and projects urea and DAP outlooks for the second half. It highlights key price drivers, inventory trends, and policy impacts shaping the 2026 market.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.