
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
Refrigerant R22 prices surged by more than 2,000 yuan per tonne within a single week during July 2026, drawing attention across China's chemical market. Procurement teams should understand what such rapid movements may signal for refrigerant supply, industrial demand and purchasing strategies.
Hydrogen peroxide markets closed H1 2026 with supply pressure driven by structural changes rather than short-term geopolitical disruption. Buyers in electronics and industrial sectors need a different risk approach for this specialised chemical.
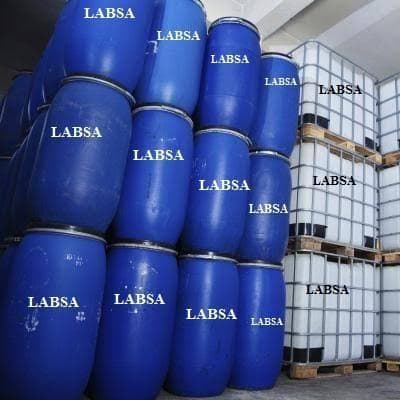
The reopening of Gulf export routes is improving n-paraffin availability, a key feedstock for LAB and LABSA production. As supply normalizes, detergent manufacturers may see easing costs in H2 2026, while buyers with existing contracts should review pricing adjustment clauses.
As crude oil prices move below $80 per barrel, specialty chemical producers are preparing for lower feedstock costs across solvents, surfactants, coating resins, and polymer additives. However, cost pass-through in specialty chemicals typically lags by 6–10 weeks, meaning Q3 contract negotiations remain critical for buyers seeking to capture expected price declines during the second half of 2026.
The formaldehyde market is entering a critical Q3 2026 period as buyers assess whether construction recovery can revive demand for wood panels and UF resins. Energy costs, housing activity and industrial confidence will shape procurement decisions across the value chain.
Fertilizer buyers face a critical Q3 2026 contracting window as urea prices fall 37%, DAP prices correct, and Hormuz supply recovery begins. Procurement decisions now depend on shipping recovery, China’s export policy, and India’s tariff decisions.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.