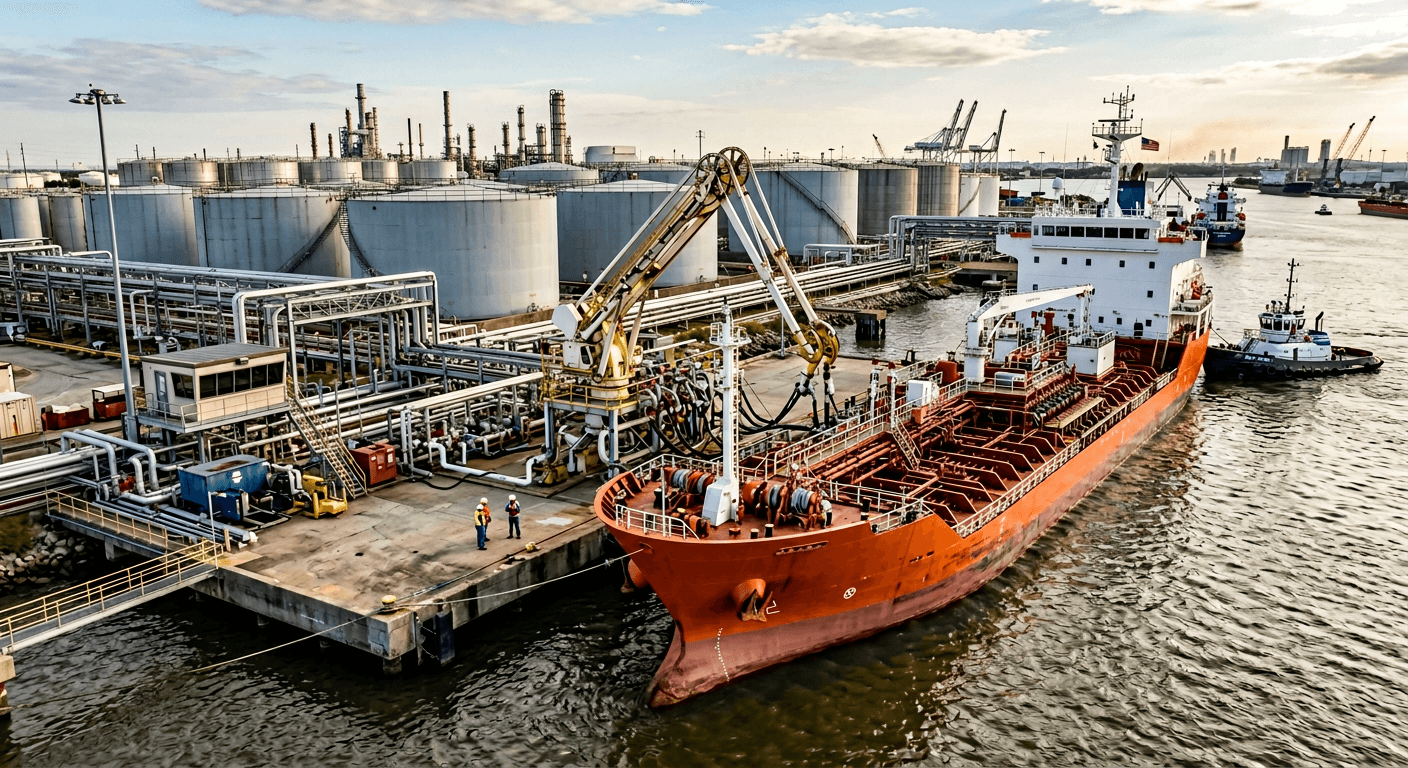
Ethanol freight activity on the US Gulf to South America route remained steady in mid-June 2026 as contract of affreightment nominations continued despite lighter spot market movement. While spot rates softened, baseline cargo demand helped maintain tanker utilization across the trade lane.
The route remains closely watched by chemical traders because ethanol and caustic soda continue to represent some of the most active cargo flows. Brazil remains a key destination for US ethanol exports, supporting consistent demand for shipping capacity.
For buyers and traders, the current softer freight environment may create a short opportunity to improve shipping terms before traditional Q3 demand growth returns.
Ethanol Freight Market Conditions on the USG-Brazil Route
The US Gulf to South America chemical shipping corridor remains an important trade route for liquid bulk chemicals. Ethanol movements continue to support activity, particularly due to steady export requirements from the United States.
Current market conditions show a mixed picture. Contract demand remains stable, but spot activity has not generated strong upward pressure on rates.
Key market observations include:
COA nominations continue providing support for vessel utilization.
Spot inquiries remain limited compared with stronger trading periods.
Freight levels have softened as immediate demand pressure has eased.
This creates a market where long-term cargo commitments remain healthy while short-term pricing becomes more negotiable.
Brazil Ethanol Imports Support Baseline Tanker Demand
Brazil continues to be one of the most active import destinations for US ethanol. Consistent cargo movement between the two regions provides stability for tanker operators.
The importance of Brazil within this trade flow comes from:
Regular import requirements from industrial users.
Established shipping routes between the US Gulf and South America.
Continued demand for reliable liquid chemical transportation.
Although spot freight conditions have weakened, steady volumes prevent a major decline in route activity.
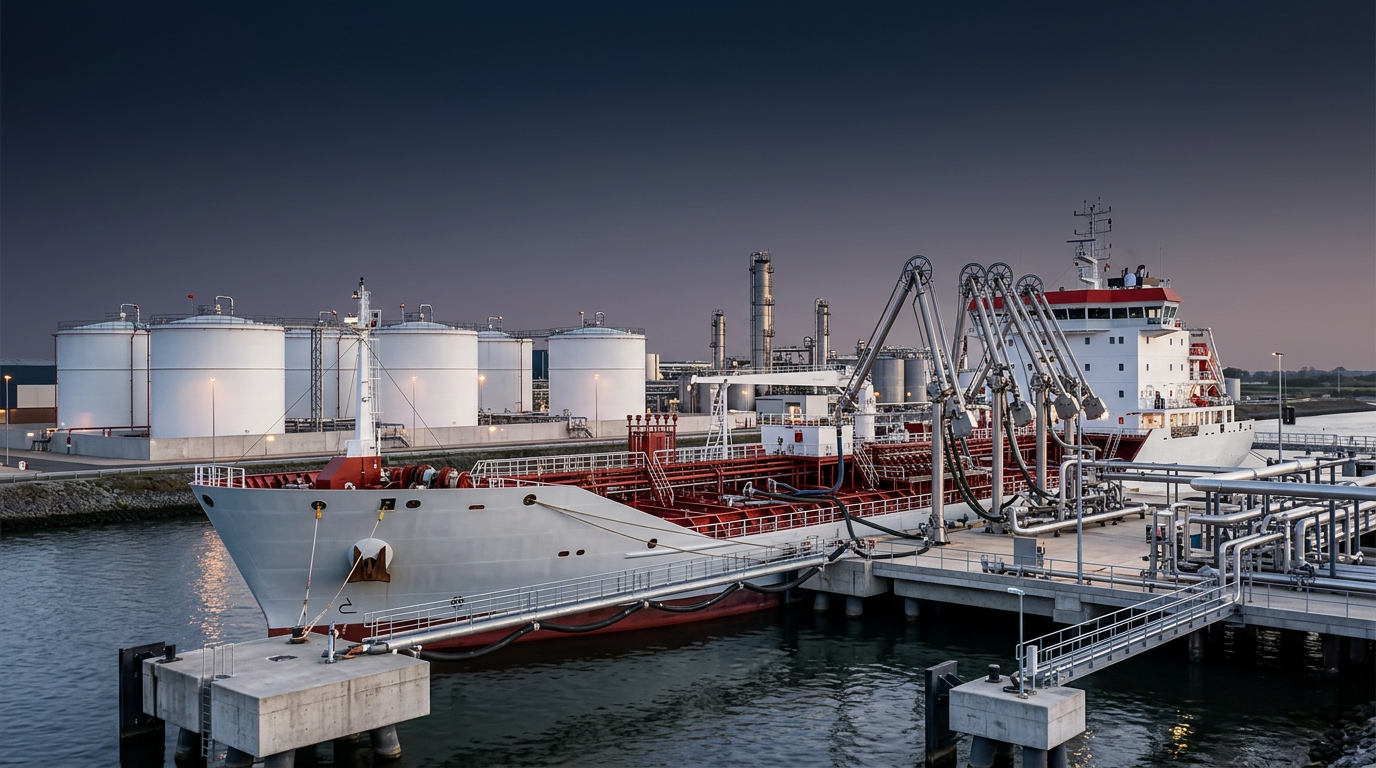
Why Spot Freight Rates Are Softening
The recent decline in spot freight rates reflects softer immediate demand rather than a collapse in ethanol trade activity. Shipping markets often react quickly when vessel availability improves or short-term inquiries slow.
Factors contributing to the softer spot environment include:
More balanced vessel availability.
Reduced urgency from spot charterers.
Lower short-term competition for tanker space.
For traders, this creates room to negotiate more attractive freight arrangements before market activity potentially strengthens later in the year.
Ethanol and Caustic Soda Shape Chemical Cargo Mix
Ethanol remains a major cargo on the US Gulf to South America route, but it shares shipping capacity with other liquid chemicals, including caustic soda.
The combination of these cargo flows influences vessel scheduling and freight availability.
Traders evaluating this route should monitor:
Ethanol export volumes.
Caustic soda shipping demand.
Vessel positioning and availability.
Seasonal changes in chemical trade activity.
Understanding the wider cargo mix helps buyers assess whether current freight conditions are temporary or part of a broader trend.
Procurement Opportunity Before Q3 Demand Growth
The current freight environment may provide a valuable negotiation window. Traditional Q3 demand increases could strengthen shipping activity and reduce available flexibility.
Buyers and traders can consider:
Reviewing upcoming shipment requirements early.
Negotiating COA terms before demand strengthens.
Comparing multiple logistics options.
Evaluating freight costs as part of total delivered economics.
A proactive approach can help companies secure better transportation conditions before market momentum changes.
Supply Chain Risks Affecting Ethanol Trade
Despite current stability, ethanol shipping markets remain exposed to external factors. Changes in energy markets, port conditions and regional demand can quickly influence freight economics.
Potential risks include:
Unexpected vessel shortages.
Higher operating costs affecting freight rates.
Changes in export demand from major producing regions.
Companies involved in ethanol trade should maintain flexible planning and continue monitoring freight developments.
Ethanol Freight Outlook for the Second Half of 2026
The near-term outlook suggests that freight conditions may remain manageable while vessel supply stays balanced. However, seasonal demand growth could provide support for rates later in the year.
Market factors to watch include:
Q3 demand increases.
Export volume trends from the US Gulf.
Brazil import requirements.
Broader liquid chemical tanker conditions.
The current environment provides buyers with improved negotiation conditions, but timing remains important.
What Traders Should Do Now
The US Gulf to South America ethanol route is showing a combination of steady trade flows and softer spot freight conditions. This balance creates an opportunity for traders to secure competitive shipping terms while market conditions remain favourable.
Companies should focus on contract flexibility, route monitoring and total logistics cost management.
Those who evaluate freight trends early can capture advantages before seasonal demand changes influence the market again. Ready to source Ethanol from verified global suppliers? Explore competitive offers on our platform today.
Ethyl Acetate CAS: 141-78-6